Education
How to Analyze a Small Multifamily Deal in 2026
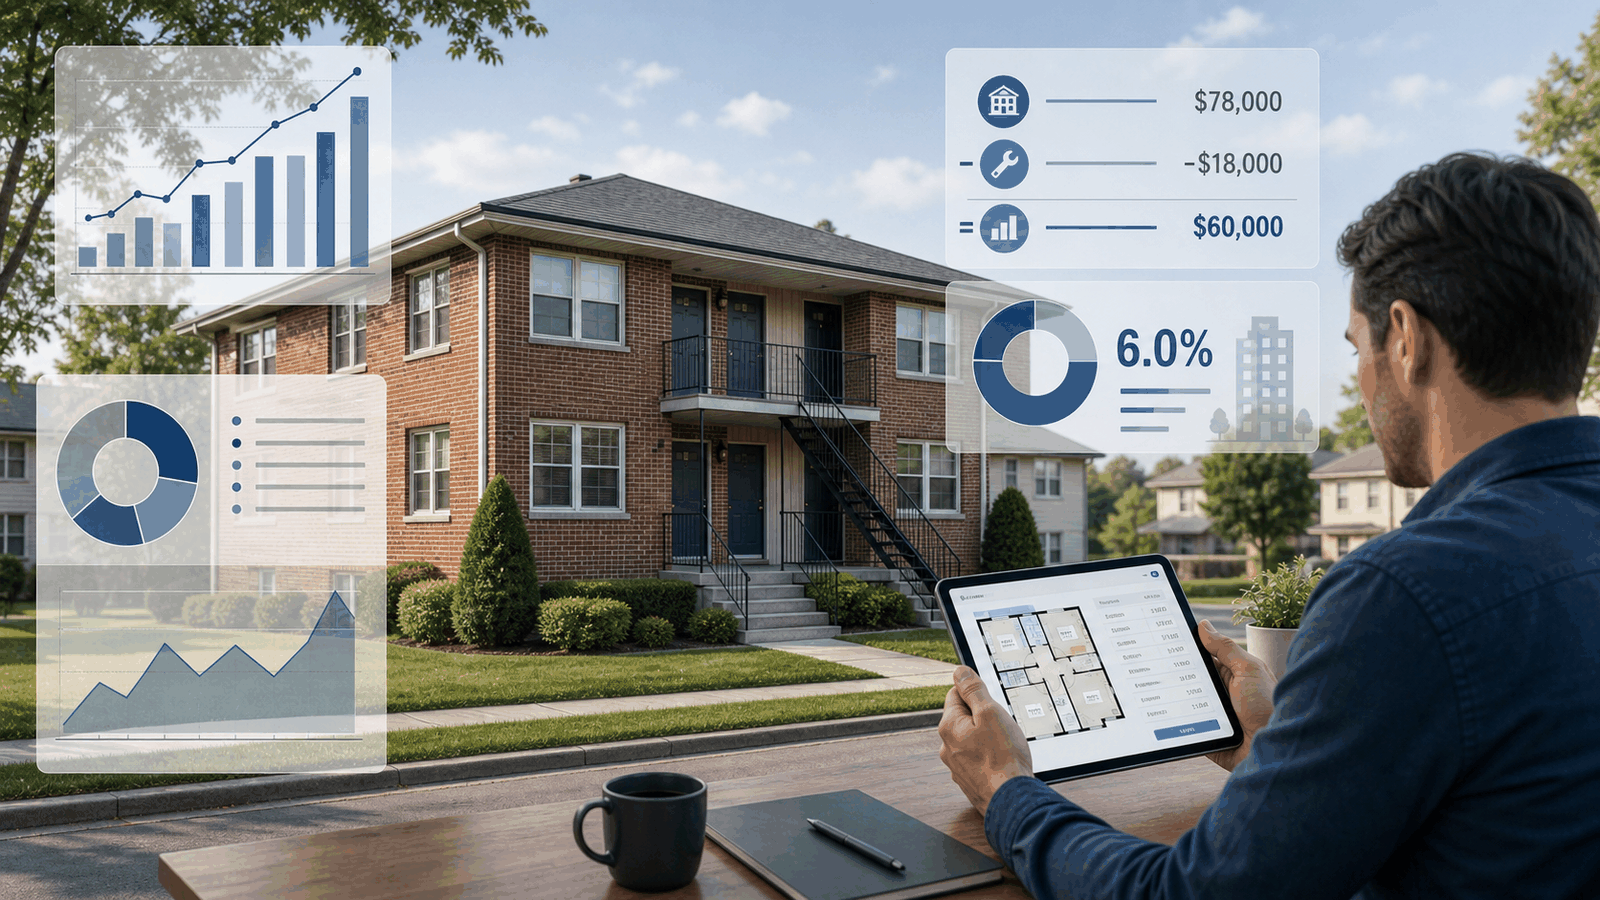
Small multifamily properties can be one of the most practical entry points into income-producing real estate. They offer more than one rent stream without the scale, complexity, or capital requirements of larger apartment assets, and for many independent investors they create a useful middle ground between single-family rentals and large commercial properties. A four-unit building is easier to understand than a 100-unit asset, but is often more financially resilient than a house with one tenant and one rent check.
That said, small multifamily is also frequently misunderstood. Many buyers focus too heavily on the asking price, projected rents, or a broker's headline cap rate. A better approach is to analyze the property as a small operating business. The question is not just whether the building looks appealing or whether the area feels promising. The real question is whether the income, expenses, financing, and risks create a deal that still makes sense after the sales pitch is stripped away.
This guide walks through that process step by step in plain language. It is written for a broad audience, including first-time investors, existing landlords looking to move up in scale, and readers who want to understand how experienced buyers think about small multifamily opportunities. For the general screening framework used on single-family and single-tenant rentals, see How to Analyze a Rental Property.
What Counts as Small Multifamily?
In practical terms, small multifamily usually means a property with 2 to 20 units. That can include duplexes, triplexes, four-plexes, townhouse clusters under one ownership structure, or smaller apartment buildings in neighborhood settings. These properties often appeal to independent investors because they combine several important advantages.
First, there are multiple income streams under one roof. If one tenant moves out of a single-family rental, income can fall to zero until the home is leased again. In a four-unit building, one vacancy hurts, but it does not eliminate all revenue. That diversification can make a meaningful difference in how stable the property feels month to month.
Second, operations can become more efficient. Maintaining four units in one location is often simpler than maintaining four houses scattered across different streets or towns. Landscaping, snow removal, exterior repairs, inspections, and tenant turnover can usually be handled more efficiently when the units are concentrated in one place.
Third, small multifamily often forces investors to think more analytically. Buyers tend to evaluate these properties based on income and expenses rather than emotion. That shift in mindset is useful because it brings the focus back to what matters: performance, durability, and risk-adjusted return.
Start With the Property Story
Before opening a spreadsheet, write a short description of the deal in plain English. This may sound simple, but it is surprisingly effective. A clear written description reveals what kind of opportunity is actually on the table.
A useful starting summary might include:
- The number of units and unit mix
- The approximate age and condition of the building
- Whether the property is fully occupied, partially occupied, or delivered vacant
- Whether the deal appears stabilized or value-add
- The broad character of the location, such as urban infill, suburban neighborhood, college-adjacent area, or workforce housing corridor
This short narrative matters because it frames every assumption that follows. A clean, fully leased four-plex in a stable suburb should not be analyzed the same way as an under-rented 10-unit building with deferred maintenance in a softer market. The analysis method is consistent, but the assumptions should reflect the actual property, not a generic template.
Gather the Data That Actually Matters
A listing can make almost any property sound attractive. The investor's job is to separate marketing language from operating reality. That starts with collecting the inputs that determine performance.
Income data
At a minimum, gather:
- Current rent roll, unit by unit
- Lease start and end dates
- Security deposit information
- Any additional income, such as laundry, parking, storage, or pet fees
- Historical occupancy, if available
- Local market rent comparables for similar units
Current rents tell part of the story, but market rents tell another. If the building is under-rented, there may be upside. If the rents are already above market, the current income may be less durable than it looks.
Expense data
The expense side is where many buyers become too optimistic. Request or estimate:
- Property taxes
- Insurance
- Water and sewer
- Trash removal
- Electric or gas for common areas or owner-paid units
- Repairs and maintenance
- Turnover costs
- Landscaping and snow removal
- Pest control
- Cleaning for common areas
- Property management
- Administrative and legal costs
- Replacement reserves for major systems
A common mistake is assuming that a self-managing owner can ignore management costs. Even if the plan is to manage the property personally, the analysis should still include a market-based management expense. That creates a more realistic picture of the asset's performance and helps answer an important question: would the property still work if management had to be outsourced later?
Financing data
Finally, gather the terms that shape actual investor returns:
- Purchase price
- Estimated closing costs
- Down payment amount
- Interest rate
- Loan term and amortization period
- Expected lender fees or points
Without these financing assumptions, it is impossible to judge whether a deal that looks acceptable on paper will still produce usable cash flow after debt service.
Build the Income Statement in the Right Order
The most useful way to analyze a small multifamily property is to treat it like a miniature business. That means building a simple operating statement from the top down.
Potential gross income
Start with potential gross income, or PGI. This is the income the property would produce if every unit rented at full market or scheduled rent for the entire year, with no vacancy and no missed payments.
This is not the same as actual income. It is a starting point.
Vacancy and credit loss
Next, subtract a realistic vacancy and credit loss allowance. Even strong properties experience turnover, late payments, or occasional nonpayment. Assuming zero vacancy usually produces a misleadingly optimistic result.
In many markets, a 5 percent vacancy assumption is a reasonable floor for a stabilized small multifamily property. In weaker submarkets, more seasonal areas, or buildings with higher turnover risk, the proper figure may be higher. The goal is not to be pessimistic for its own sake. The goal is to respect reality.
Effective gross income
After subtracting vacancy and credit loss from potential gross income, the result is effective gross income. This is the income the property is realistically expected to collect.
Operating expenses
Then subtract normal operating expenses. These are the recurring costs of running the property and keeping it income-producing. They include taxes, insurance, utilities paid by ownership, repairs, routine maintenance, management, and other ordinary operating costs.
They do not include mortgage payments, capital expenditures associated with major repositioning, depreciation, or the buyer's income taxes. Those come later or belong in different parts of the analysis.
Net operating income
What remains after operating expenses is net operating income, or NOI. This is one of the most important numbers in real estate because it measures the property's income power before financing. It allows investors to compare properties on a more consistent basis, even when they plan to finance them differently.
Why NOI Matters More Than the Listing Pitch
NOI is often where real understanding begins. A building with strong gross rent can still be a weak asset if insurance, maintenance, utilities, and taxes consume too much of the income. On the other hand, a property with ordinary-looking rent can become attractive if expenses are well controlled and the income is stable.
This is also why headline marketing numbers deserve skepticism. If a listing advertises an unusually high cap rate, the first question should not be, "How fast can this be bought?" It should be, "What assumptions are being used to produce that cap rate?"
The quality of the NOI matters just as much as the size of the NOI. Income from leases that are near market and sustained by a healthy local rental base is more reliable than income propped up by one-time concessions, aggressive assumptions, or neglected maintenance.
Use Cap Rate as a Pricing Tool, Not a Decision Shortcut
Once NOI is established, the next common metric is the capitalization rate, or cap rate. In simple terms, the cap rate tells how much annual pre-debt income the property produces relative to its price.
A higher cap rate generally means more income for each dollar invested in the purchase. A lower cap rate generally means the market is pricing the property more aggressively, often because the asset is perceived as safer, newer, better located, or more desirable.
Cap rate is useful, but limited. It can help answer questions like:
- Is the seller's price in line with other similar properties?
- Is this deal being offered at a premium or a discount relative to its income?
- What price would make the deal more compelling based on a target return threshold?
What cap rate cannot do on its own is tell the whole story. It says nothing about financing, future capital needs, management burden, tenant quality, or how much work will be required to reach the advertised income level. Cap rate is a starting point for valuation, not a substitute for complete analysis.
Add Financing to See the Deal the Way an Investor Experiences It
Many properties look acceptable when viewed through cap rate alone. The picture often changes when debt is added. Financing determines whether the property actually produces cash flow for the investor or merely supports the loan.
Two measures are especially helpful here: debt service coverage ratio and cash-on-cash return.
Debt service coverage ratio
Debt service coverage ratio, often shortened to DSCR, measures how comfortably NOI covers the annual mortgage payment. A DSCR above 1.0 means the property generates enough operating income to pay its debt service. A DSCR below 1.0 means the property does not fully support its own financing.
This ratio matters because a deal with very thin coverage may still close, but it leaves little room for vacancy, repairs, tax increases, or insurance spikes. In practice, that means the investor may be forced to contribute additional cash even if the property appears occupied and active.
Cash-on-cash return
Cash-on-cash return measures the annual pre-tax cash flow relative to the total cash invested up front. That usually includes the down payment, closing costs, and any immediate repair budget required to stabilize the property.
This metric is often one of the most useful for ordinary investors because it answers a basic question: how hard is the invested cash working? A property can have an acceptable cap rate but still produce underwhelming cash-on-cash returns if debt terms are unfavorable or the price is too high.
A Simple Example: Why a Decent-Looking Deal Can Still Be Tight
Imagine a four-unit property in a decent suburban location. Each unit could likely rent for 1,800 per month, producing potential annual rent of 86,400. If a 5 percent vacancy allowance is used, effective gross income falls to 82,080.
Now assume annual operating expenses look like this:
- Taxes: 9,000
- Insurance: 4,500
- Water, sewer, and trash: 6,000
- Repairs and maintenance: 7,000
- Contract services and common-area costs: 3,000
- Property management: 6,566
- Miscellaneous and reserve allowance: 2,500
That creates total operating expenses of 38,566 and NOI of 43,514.
At a purchase price of 800,000, that NOI implies a cap rate of roughly 5.4 percent. At first glance, that may sound acceptable depending on the market. But now add financing: 25 percent down, a loan of 600,000, and an interest rate in the mid-6 percent range on a 30-year amortization schedule. The annual debt service could end up slightly above the NOI.
That means the building may not fully pay for itself in year one, despite being fully functional and reasonably occupied. This is where many investors get into trouble. The property is not obviously broken, but it is priced tightly enough that small changes in expenses or financing can turn it into a weak performer.
The lesson is important: a property does not need to be disastrous to be a poor fit. It only needs to be priced aggressively enough that the income cushion disappears.
Stress-Test Before Trusting the Base Case
A good underwriting model should not answer only one question. It should answer several versions of the same question under different conditions.
Stress-testing means changing assumptions to see how resilient the deal really is. Useful scenarios include:
- Vacancy rises from 5 percent to 8 or 10 percent
- Insurance increases sharply after acquisition
- Property taxes are reassessed upward after the sale
- Expected rent growth never materializes
- Repair costs run higher than budgeted in the first two years
A property that still works reasonably well under these scenarios is often more attractive than one with a prettier base-case spreadsheet but no margin for error. The most dangerous deals are not always the obviously bad ones. They are often the deals that look respectable until ordinary friction enters the picture.
Pay Attention to the Risk You Cannot See in a Spreadsheet
Not all important information shows up in a pro forma. Some of the most expensive surprises come from physical condition and local market structure.
Physical risk
A small multifamily property should be evaluated for:
- Roof age and condition
- Plumbing and electrical quality
- Foundation issues or water intrusion
- Boiler, furnace, water heater, or HVAC condition
- Safety compliance and code exposure
- Deferred maintenance hidden behind cosmetic updates
A newly painted hallway does not offset a failing sewer line. Cosmetic improvements are often the easiest part of ownership. Building systems are where the serious money tends to go.
Market risk
The surrounding submarket matters just as much as the building itself. Important questions include:
- Is the local job base expanding, stable, or weakening?
- Is there significant new apartment supply nearby?
- Are rents supported by local incomes, or are they already stretched?
- Is the area attractive to long-term renters, students, young families, or workforce tenants?
- Are local landlord regulations tightening in ways that could affect operations or rent growth?
The stronger the local rental ecosystem, the more forgiving the asset can be. In fragile markets, even competent ownership may struggle against weak demand or oversupply.
Define What a Good Deal Means Before Looking at Deals
One of the simplest ways to improve decision-making is to define minimum standards before falling in love with a property. Investors often become flexible at exactly the wrong moment, especially after spending time touring units, negotiating, or imagining future upside.
Clear standards can include:
- A minimum acceptable cash-on-cash return in year one
- A minimum DSCR threshold
- A preferred hold period
- A maximum renovation burden
- A target neighborhood profile
- A limit on how much rent growth must occur for the deal to work
This does not eliminate judgment. It improves judgment. A buyer with clear standards can evaluate opportunities more calmly because the framework already exists before the emotions of the specific deal begin to influence the analysis.
The Best Insight: Small Multifamily Is a Test of Discipline
Perhaps the most underrated truth about small multifamily investing is that success often comes less from finding a magical property and more from avoiding the urge to rationalize mediocre ones.
Many deals are not terrible. They are simply too thin, too optimistic, too management-heavy, too dependent on future rent growth, or too vulnerable to rising expenses. Those are exactly the deals that often absorb time and capital while delivering disappointing results.
A strong small multifamily investment usually looks somewhat boring on paper. The rents are believable. The expenses are not artificially compressed. The debt is supportable. The building has issues, but not fatal ones. The market is steady rather than spectacular. And the return works without heroic assumptions.
That may not be the most exciting kind of deal to talk about, but it is often the kind that compounds wealth more reliably over time.
Final Thought
To analyze a small multifamily property well, treat it as a business with walls, roofs, tenants, and cash flow rather than as a story about appreciation or a shortcut to passive income. Start with realistic income, subtract honest expenses, test the financing, challenge the assumptions, and look hard at the physical and market risks.
When that process is done carefully, the answer becomes clearer. Some properties reveal themselves as stable, durable income assets. Others reveal themselves as expensive optimism wearing the clothes of an investment opportunity.
That distinction is where better real estate decisions begin.
Succession Holding LLC publishes independent real estate education and market analysis. Nothing in this article constitutes investment advice or a recommendation to buy or sell any asset. Investors should consult a licensed tax advisor and real estate professional in their jurisdiction before making acquisition decisions.