Investing
Single-Family vs. Multi-Family: Choosing Your Investment Strategy
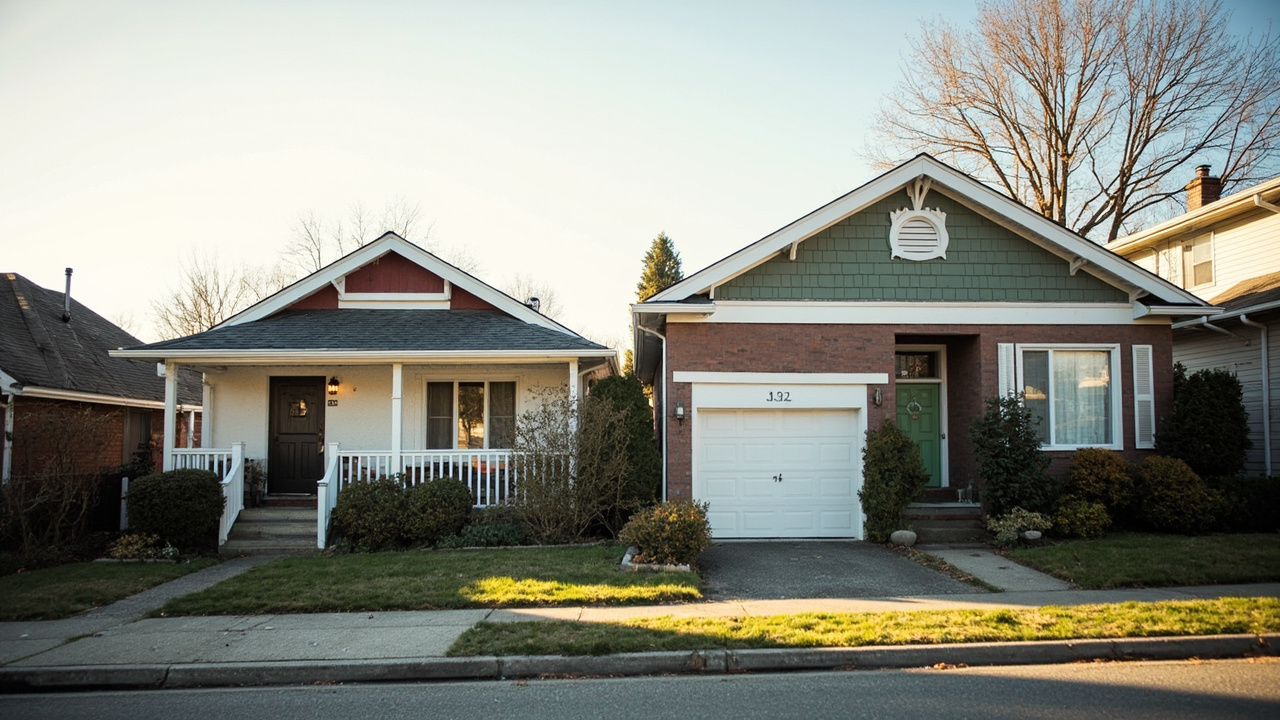
Single-family and multi-family properties represent the two most common residential investment strategies, and each has distinct advantages, challenges, and return profiles. Understanding the practical differences between them — not just the theoretical ones — helps you choose the right starting point for your portfolio based on your capital, time horizon, and management bandwidth.
Single-Family Rentals: Accessibility and Simplicity
Single-family rentals are the most accessible entry point into real estate investing. They finance with conventional loans, require relatively modest capital to acquire, and are straightforward to manage for most first-time investors. The financing for a single-family rental requires 15-20% down with competitive rates for well-qualified borrowers, and the property can often be self-managed without specialized knowledge.
The primary advantage of a single-family rental is exit flexibility. When you are ready to sell, there is a large pool of potential buyers — both investors and owner-occupants who might move in eventually. This liquidity means single-family homes tend to appreciate at or above market averages and can be sold more quickly in a normal market. The downside is income concentration: a single-family rental is all-or-nothing income. If the tenant moves out, you have zero rental income until the property is re-leased, and re-leasing a single-family home typically takes 30-60 days.
Location matters more for single-family rentals than for multi-family, because you are competing with all the other homes in the submarket for the same tenant pool. A single-family home in a desirable school district commands strong rents; one in a declining neighborhood may sit vacant longer and appreciate more slowly.
Multi-Family Rentals: Income Diversity and Scale
Multi-family properties — duplexes, triplexes, fourplexes, and larger apartment buildings — offer income diversity that single-family properties cannot. In a fourplex, if one unit turns over, you still have three units generating income. This diversification reduces income volatility and provides a buffer during periods of vacancy or rent reduction.
The economics of multi-family are also more favorable on a per-unit basis. Acquisition costs, maintenance costs, and management costs are spread across multiple units, which means the overhead per unit is lower. A property manager charging 8% of gross rent on a single-family home charges the same percentage on a fourplex generating four times the income, which is a more efficient arrangement. Cap rates on multi-family properties tend to be more transparent because income is documented on tax returns, and lenders treat multi-family as a distinct asset class with established underwriting standards.
The primary challenges with multi-family are higher entry capital requirements, more complex financing, and higher management demands. A fourplex requires the same level of property management infrastructure as a single-family home but with four times the income to manage. Tenants in multi-family properties may have different expectations around maintenance response times, and turnover in one unit affects a larger percentage of your overall income.
Choosing Based on Your Situation
For investors starting with under $100,000 in capital, single-family homes in secondary markets are often the more accessible path. The conventional loan market is deep and competitive for single-family homes, and there are more distressed or below-market opportunities in this segment.
For investors who already own one or two single-family rentals and are looking to scale, a small multi-family property can be an efficient next step — particularly a duplex or fourplex where you can house-hack one unit and use an FHA loan to reduce the down payment requirement to 3.5%. This strategy is one of the most capital-efficient paths to building a multi-unit portfolio, and it is available to first-time investors who can occupy one of the units for at least 12 months.
A Worked Example: Same Capital, Two Strategies
Consider an investor with $150,000 to deploy, comparing a single-family rental at $400,000 against a duplex at $400,000 in the same Anchorage submarket. The single-family is 1,800 square feet, three-bedroom, two-bathroom, currently rented at $2,400 per month. The duplex is two 1,000-square-foot units, two-bedroom, one-bathroom, currently rented at $1,500 per side. Both are 25-year-old construction. Both require 25% down ($100,000), leaving $50,000 for closing costs and reserves. All figures below are hypothetical, based on these assumed inputs — verify taxes, insurance, rents, and rates for any real property before using them in a purchase decision.
For the single-family, gross monthly rent is $2,400, or $28,800 annually. Operating expenses — property taxes ($4,800), insurance ($1,800), 5% vacancy ($1,440), maintenance ($1,800), self-management at 0% — total $9,840. NOI is $18,960. Cap rate: $18,960 ÷ $400,000 = 4.74%. Debt service on $300,000 at 6.5% interest is $1,896 per month or $22,752 annually. Cash flow: $18,960 − $22,752 = −$3,792 annual cash flow, or about $316 per month negative.
For the duplex, gross monthly rent is $3,000, or $36,000 annually. Operating expenses — property taxes ($5,400), insurance ($2,400), 5% vacancy ($1,800), maintenance ($2,400) — total $12,000. NOI is $24,000. Cap rate: $24,000 ÷ $400,000 = 6.0%. Debt service is the same $22,752 annually. Cash flow: $24,000 − $22,752 = $1,248 annual cash flow, or about $104 per month positive.
The same purchase price, same financing, same neighborhood — and a $5,040 swing in annual cash flow. The duplex produces positive cash flow while the single-family produces negative cash flow. This is the core mathematical advantage of small multi-family: two income streams against one debt service produces a meaningfully different return profile.
Common Single-Family vs Multi-Family Mistakes
Comparing cap rates without adjusting for risk. Single-family rentals typically trade at lower cap rates because they have lower perceived management complexity, faster tenant turnover, and broader buyer demand at resale. A duplex at a 6% cap rate is not 1.26 percentage points "better" than a single-family at a 4.74% cap rate — the risk premium reflects liquidity, tenant base, and resale market depth.
Underestimating the management overhead of two tenants. Two tenants means two leases, two security deposit accounting trails, two points of contact, and double the chance of a tenant issue in any given month. For self-managing investors, this is manageable but real. For investors using a property manager, the management fee typically scales with the number of units — 8–10% of gross rent is standard, and that doubles the absolute management cost on a duplex.
Ignoring financing differences. Conventional lenders treat 1–4 unit properties under the same residential underwriting framework, but the analysis for a duplex differs. Lenders calculate the rental income for a duplex at 75% of gross rent (rather than 100%) when determining qualifying income for the loan. This can reduce the loan amount an investor qualifies for relative to the single-family.
Assuming exit liquidity is identical. Single-family rentals sell to both investors and owner-occupants, which broadens the buyer pool. Duplexes sell primarily to investors. In a market downturn, duplexes may take longer to sell and may require deeper price reductions because the buyer pool narrows.
Decision Checklist: Single-Family or Multi-Family
- Have you modeled both property types at the actual financing terms you qualify for?
- Have you accounted for the higher property tax burden on the multi-family property?
- Have you calculated the marginal management cost (self-managed vs professional) for the second unit?
- Does your lending institution treat the rental income from both units at 75% for qualifying purposes?
- Have you inspected both properties with attention to shared systems — common utilities, shared roofs, shared parking?
- Have you reviewed the duplex's separate utility metering, or is the property on a single meter with internal allocation?
- Are the leases in place at the duplex at or near market rent, or will you need to reset rents at turnover?
When This Comparison Doesn't Apply
The single-family vs multi-family framework applies to stabilized, income-producing residential properties in conventional rental markets. It does not apply to short-term or vacation rental markets, where the income profile, management intensity, and regulatory environment differ materially. It does not apply to commercial multi-tenant properties — five or more units typically fall under commercial underwriting with different debt structures, different tenant law, and different appraisal frameworks. It does not apply to condominium or cooperative units, where HOA dues and association rules substitute for some landlord responsibilities. Investors should match the comparison framework to the actual asset class under consideration.